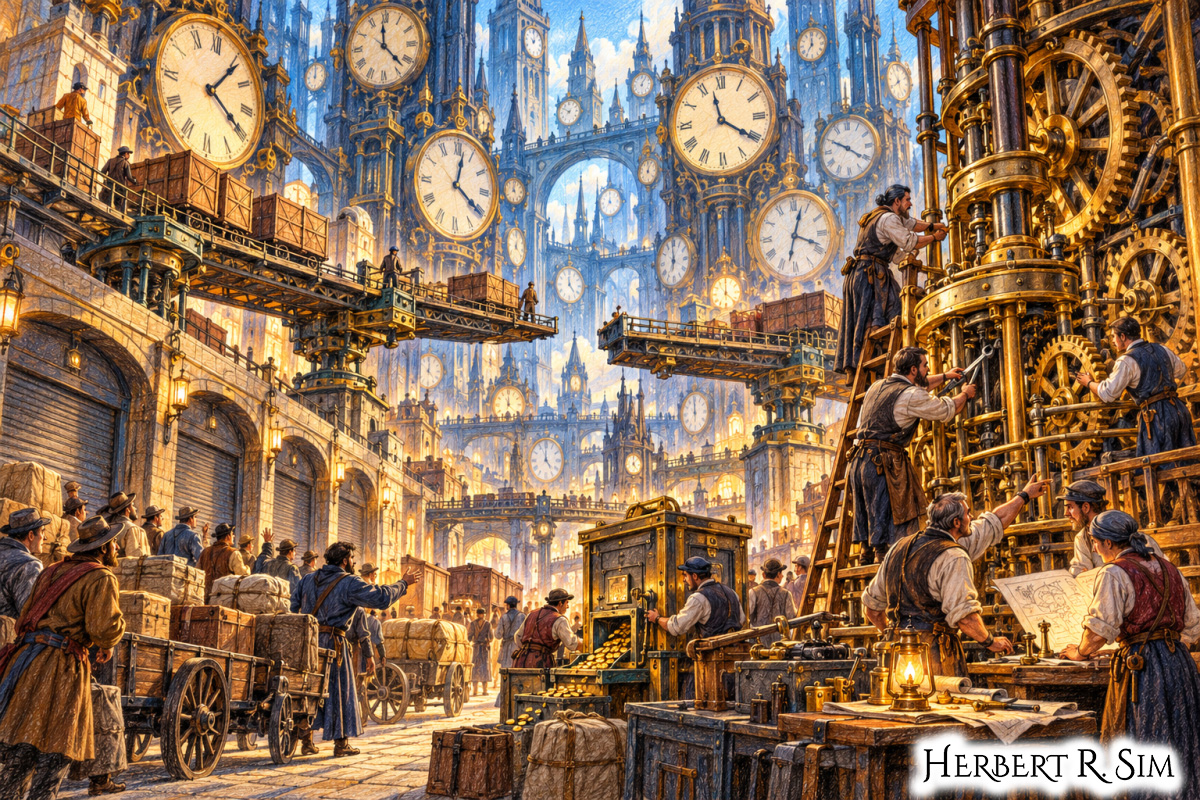
My illustration entitled: “The City of Unsynchronised Clocks” – An immense trading metropolis operates beneath hundreds of monumental clocks, each showing a different hour. Goods arrive after warehouses close, payment mechanisms activate too late, and transport bridges rotate out of alignment. Citizens gather around a shared clockwork mechanism to coordinate repairs.
A group of independent traders establishes an alternative marketplace. Its founders promise lower charges, greater privacy and less dependence on established intermediaries. Early participants welcome the opportunity to build something different.
Yet months later, customers struggle to find sellers. Merchants receive payments they cannot readily use elsewhere. Complaints accumulate, deliveries become unreliable and members discover that withdrawing their resources is harder than joining.
The marketplace remains formally independent. Its participants possess fewer practical options than they expected.
This possibility deserves serious attention within Counter Economics. An alternative earns its value through reliable opportunities to exchange, preserve resources and reconsider commitments. Its origins or ambitions cannot establish those achievements.
Four failure conditions are particularly important: inadequate liquidity, ineffective protection against fraud, poor coordination and obstructed exit. Understanding their interaction helps distinguish a repairable difficulty from an arrangement that should change fundamentally or close.
What Counts as Failure?
A parallel market offers an additional route for economic activity alongside established arrangements. It might connect producers directly, organise cooperative purchasing or support exchange through different payment methods.
Some alternatives remain small by choice. Limited scale does not independently establish failure.
The relevant question is whether the market performs the functions participants reasonably rely on it to provide. Can buyers obtain useful goods? Can sellers receive spendable value? Are promises understandable and remedies credible?
Failure occurs when significant shortcomings persist, undermine those functions and lack an adequate response.
Assessment should consider severity, duration and distribution. A minor inconvenience for a well-resourced participant may threaten the livelihood of someone who has committed most of their working capital.
Liquidity: Having Value Without a Usable Counterparty
Liquidity concerns the ability to exchange within a reasonable time and at an acceptable cost. It requires willing counterparties, suitable quantities and workable arrangements for completing transactions.
A market can display attractive prices while offering little actual trading capacity.
Imagine a merchant accepting a community trading credit. The account shows a substantial balance, but few suppliers accept it and available sellers offer little the merchant needs.
The recorded balance cannot readily support ordinary business obligations.
Similar difficulties can arise where an asset trades regularly in small quantities but becomes expensive to exchange when someone needs a larger amount.
Participants need an honest understanding of usable trading opportunities. A quoted price or account balance alone cannot establish access to purchasing power.
Promises of Liquidity Can Conceal Other Risks
A market operator may respond to limited trading by promising conversion into another form of payment.
That promise creates a further obligation. Participants need to understand what resources support it, under which conditions conversion occurs and what happens when demand for withdrawal rises.
Temporary difficulty meeting immediate obligations differs from having insufficient assets to meet total commitments. Confusing these conditions can postpone necessary action.
Borrowing may bridge a temporary timing gap. It cannot by itself repair continuing losses or eliminate a shortage of real resources.
Operators should avoid presenting additional commitments as a substitute for examining the underlying problem. Reliable disclosure and independent scrutiny become especially important when participants cannot directly verify the resources supporting a promise.
Fraud: Independence Does Not Establish Honesty
An alternative marketplace can attract honest innovators and people seeking to exploit trust.
A seller may misdescribe goods. An operator may conceal losses. Participants may fabricate reviews or make promises they have no realistic intention of fulfilling.
A shared commitment to independence cannot resolve these risks.
Indeed, loyalty to the project may discourage complaints. Members may fear that reporting misconduct will damage confidence or provide ammunition to critics.
That reaction protects the organisation’s image at the expense of its participants.
A credible alternative should welcome relevant evidence, distinguish mistakes from deception and investigate complaints proportionately. Protecting people against misconduct belongs within its purpose. Criticism should be assessed through its substance rather than dismissed because it threatens a reassuring collective story.
Verification Must Match the Promise
Different risks require different evidence.
A payment record may establish that funds moved without proving that goods met their description. A photograph may show equipment without establishing ownership or condition. A review may describe a genuine experience while revealing little about the seller’s ability to fulfil a larger order.
Bitcoin and other payment arrangements illustrate this distinction. Verifying a payment does not independently resolve whether the surrounding agreement was performed honestly.
Markets need proportionate ways to establish specifications, delivery, authority and responsibility.
Inspection, limited records and independent review can help. Their costs should reflect the transaction’s significance. Excessive verification can exclude small participants, while inadequate verification leaves them exposed to losses they cannot absorb.
My illustration “The City of Unsynchronised Clocks” work-in-progress. The art represents that independent participants still need workable coordination to exchange reliably.
Coordination: Independent Decisions Still Need to Fit Together
A marketplace can fail even when participants act honestly.
Goods may arrive after receiving facilities close. Payment schedules may conflict with supplier obligations. Different descriptions or technical formats may prevent buyers and sellers from understanding one another.
These failures concern coordination.
Independence gives people room to make decisions, but exchange requires enough agreement for those decisions to connect.
Shared standards, clear settlement schedules and dependable communication can support cooperation without requiring one organisation to determine every activity.
Someone must nevertheless maintain these arrangements and respond when they break down. A market that relies indefinitely on unpaid improvisation may become fragile as participation grows. Governance should identify responsibilities, resources and procedures for changing common arrangements.
How Failures Reinforce One Another
Liquidity, fraud and coordination problems can form a destructive cycle.
Suppose delayed settlement prevents merchants from buying replacement stock. Reduced availability discourages customers. Lower trading activity makes conversion harder, while uncertainty encourages withdrawals.
If organisers conceal these difficulties, legitimate operational problems become failures of disclosure. Participants then struggle to distinguish a temporary interruption from a deeper shortage.
Trust deteriorates further.
This interaction matters because treating each symptom separately may miss the structure causing them. Advertising can attract new participants without repairing settlement. Restricting withdrawals can delay visible failure while increasing dependence.
Recovery requires identifying the original obligations, the available resources and the connections through which disruption spreads. Confidence should follow credible repair rather than substitute for it.
Exit Is Part of the Market’s Design
People should understand how participation ends before committing significant resources.
Can they withdraw legitimately held funds? Can they retrieve records, complete outstanding orders and move to another provider? Which obligations continue after departure?
Exit conditions should distinguish genuine costs from measures intended chiefly to prevent movement.
Some delays may be necessary to settle transactions, investigate misconduct or protect other participants. Their purpose, scope and review conditions should be clear.
An unexplained restriction becomes particularly troubling where operators introduce it only after dependence has developed.
A parallel market cannot demonstrate economic freedom merely by allowing easy entry. It must also provide a realistic account of departure, including circumstances in which resources cannot immediately be recovered.
Repair Requires Evidence and Authority
Some failures can be corrected through improved processes, revised commitments or additional resources.
A repair plan should identify the problem, specify responsibilities and establish observable milestones. Participants need enough information to assess whether the proposed changes address the cause.
Independent review may be necessary where organisers’ own conduct is disputed.
Emergency powers should remain bounded. A temporary intervention to preserve records differs from unlimited authority to change balances or prevent criticism.
Repair should also recognise unequal burdens. Small traders may need immediate access to records or partial settlement to continue operating.
The aim is to restore workable cooperation while protecting those affected. Saving the institution is worthwhile only insofar as its continued operation serves defensible human and economic purposes.
Sometimes Closure Protects Sovereignty Better
A market may lack sufficient demand, resources or trustworthy administration to continue.
In such circumstances, an orderly wind-down can protect participants better than repeated appeals for loyalty or additional contributions.
Planning should address outstanding claims, preservation of evidence, communications and the return or allocation of remaining resources through appropriate procedures.
Responsibilities do not disappear when the trading website closes.
Participants may also need help moving records and relationships elsewhere. Privacy should remain protected during that transition.
Ending an unsuccessful arrangement does not establish that all alternatives are futile. It demonstrates a willingness to distinguish a broader programme of economic independence from the survival of a particular organisation. That distinction is essential to responsible experimentation.
Judge Alternatives by What Participants Can Actually Do
Evaluation should track completed trades, settlement delays, usable conversion opportunities, unresolved complaints and the practical costs of leaving.
Figures require context. Rising registrations may coexist with declining activity. A low complaint count may reflect an inaccessible procedure. Successful withdrawals by small users may conceal restrictions affecting larger commitments.
Evidence should describe participants’ experience, including those whose losses are easiest to overlook.
Counter Economics becomes stronger when it examines failure openly and treats correction, exit and closure as legitimate possibilities.
A parallel market advances economic sovereignty when people can exchange reliably, challenge broken promises and leave on understandable terms. When those capabilities disappear, its claim to provide an alternative must be reconsidered.